Helping a relative abroad stay connected can be a useful, practical form of support. But small mobile top-ups can become a substantial expense when several people need help or requests arrive throughout the month. A clear arrangement protects your budget while giving your family member a better idea of what they can rely on.
The transaction itself may be straightforward. With Numio, for example, you start by choosing a destination country and entering a mobile number, then select an amount and pay. The more important household decision comes before checkout: whether phone credit meets the need, how much you can afford and what you will do if a payment or delivery is unresolved.
First, check whether mobile credit meets your family member’s needs
A mobile top-up adds credit to a supported phone account; it is not the same as sending unrestricted cash. Your relative may need airtime for calls, a particular data package or money for an unrelated bill. Do not assume that a balance increase automatically buys the bundle they want. Ask what they need and how their operator lets them use the credit.
Next, check destination and operator support before making a promise. The Numio mobile top-up coverage directory allows searches by country or dialling code and states that supported operators are shown before checkout. A country appearing in a directory is a useful starting point, but you should still check the actual number and available options.
It also helps to establish who uses the number and whether it is still active. A saved contact may be outdated, or a relative may have changed networks. Ask the recipient to confirm the number and the service they expect to receive. This short conversation can prevent a successful payment from becoming an unhelpful purchase.
Set a monthly support limit that fits your own budget
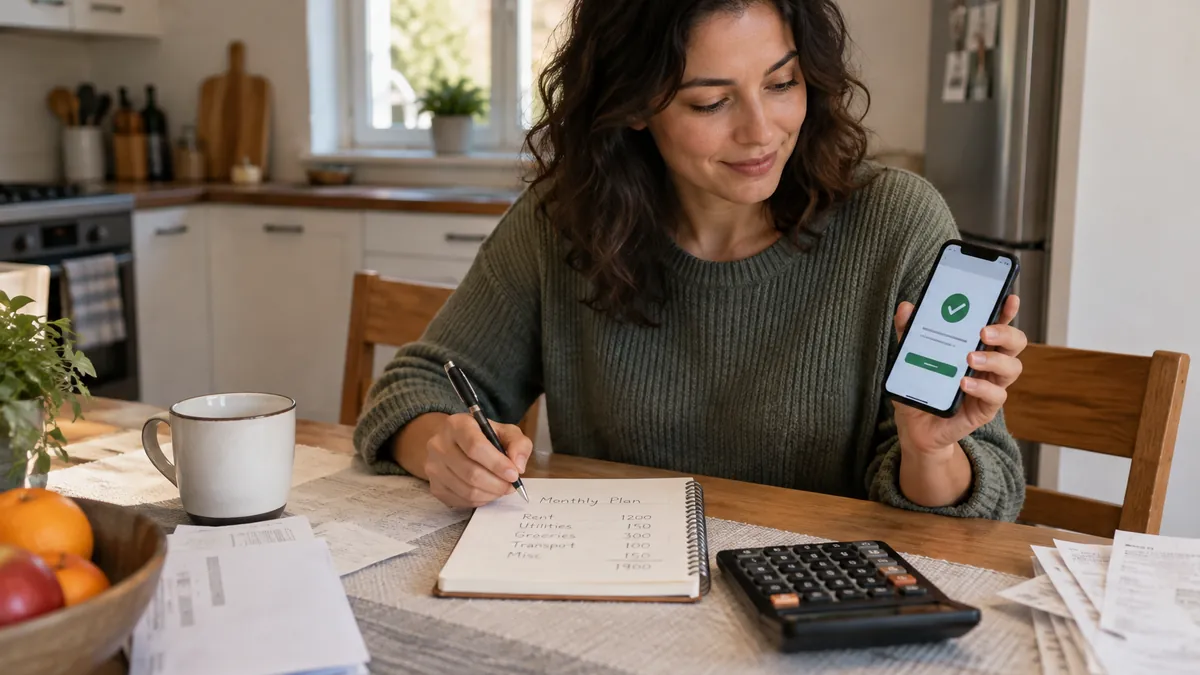
Treat regular phone-credit support as a spending category rather than a series of isolated favors. Start with take-home income, essential bills, debt commitments and planned savings. Then decide what room remains for family support. If your income varies, use a cautious estimate rather than assuming every month will match your strongest earnings.
The Consumer Financial Protection Bureau’s Budgeting: How to create a budget and stick with it provides a framework for recording income, tracking spending and mapping bill dates. Those steps help you judge both affordability and timing: a top-up may fit the monthly total but still leave you short before rent is due.
For example, suppose you take home £2,100 each month. Essential costs and minimum debt payments total £1,650, while planned savings take £200. That leaves £250 for flexible spending. You might allocate £30 of that amount to family phone support, leaving £220 for your other flexible needs. The £30 is a spending ceiling, including any checkout charges, not a promise to buy £30 worth of advertised credit regardless of the final cost.
You could divide that allowance into two planned purchases of up to £12 each, with £6 left for an occasional extra request or a change in cost. Any unused amount can remain unspent. Agree in advance whether an extra top-up uses next month’s allowance or requires a separate decision; otherwise, exceptions can quietly become the normal arrangement.
Compare the checkout cost with the credit your relative will receive
Keep two figures separate: what leaves your account and what reaches the recipient’s mobile account. They may be shown in different currencies, and the available credit amounts may not match the sum you originally intended to send. Compare the final checkout total with the stated mobile credit rather than judging value from a headline amount alone.
Check any charges and currency information displayed before confirming. If your payment card uses a different currency from the checkout, check your card provider’s terms for conversion or foreign-transaction costs. These are potential costs to investigate, not charges you should assume every service or card will apply.
Available denominations matter too. Numio states that the final top-up amount depends on the amounts supported by the operator and may be rounded down to the nearest supported amount. If you were aiming for a particular bundle price, a slightly smaller balance might not meet that need. Confirm the displayed amount and ask the recipient whether it will be sufficient.
When comparing services, use the same destination, number and intended outcome. A cheaper purchase is not necessarily better if it provides less useful credit. Likewise, buying a larger amount simply to improve an apparent rate can defeat your budget. The useful question is: what is the total cost of meeting this person’s actual phone need?
Check the number, amount and request before paying
Before checkout, take a moment to review the details as if you were making a new payment, even when you have helped the same person before. Copying a number reduces typing errors, but it does not prove that the copied number is correct. Confirm the destination country and check that the number is entered in the format the service requests.
- Recipient: Confirm the current mobile number through a trusted conversation or existing contact.
- Destination and operator: Check the country and the supported operator identified during the process.
- Credit: Review the final amount and whether it meets the recipient’s intended use.
- Payment: Check the total charge, currency and confirmation email address.
- Budget: Make sure the purchase fits the remaining family-support allowance.
Unexpected urgency deserves a separate identity check. A message claiming that a relative has lost their phone, changed numbers or needs immediate help may be genuine, but it can also be an impersonation attempt. Contact them using a number you already trust, or check with another trusted family member, rather than relying only on the contact details in the request.
The Federal Trade Commission’s Scammers Use Fake Emergencies To Steal Your Money describes warning signs such as pressure to act quickly, demands for secrecy and cloned voices. A familiar-sounding voice is not enough to bypass verification. Pause the transaction if the story or identity remains uncertain.
This final review also matters because submitted mobile credit may not be reversible. Numio warns users to check the destination, number and amount before confirming. Do not treat cancellation or a refund as a reliable way to correct an avoidable entry mistake.
Track delivery and resolve a top-up that does not arrive
After paying, save the order reference, confirmation email, amount charged and intended number. A simple note or spreadsheet is enough. Record the transaction date and status as well, so you can distinguish a completed top-up from a payment that is still being processed.
Do not assume that a bank notification proves the phone has received credit. Payment confirmation and delivery are different stages. Numio describes order tracking through payment, processing and delivery, with submission to the operator after payment confirmation. Check the order status and ask the recipient to check their balance before concluding that the purchase has failed.
If the result is unclear, avoid immediately buying the same top-up again. You could create a duplicate expense if the first order later completes. Look for status updates and use the service’s official support route, providing the order reference and a brief description of the problem. Never send full card numbers, passwords or other sensitive payment details in a support message.
For an unsuccessful Numio top-up, the stated next steps depend on payment status and its Refund Policy: a pending authorization may be released or a refund may be issued. Neither outcome should be assumed to happen instantly. Keep unresolved purchases visible in your spending record, and only mark money as returned when your payment account confirms it.
Review the arrangement before making support a recurring commitment
After a month or two, compare what you planned with what you actually spent. Include extra requests and any card-related charges, not just the credit amounts. If your £30 limit repeatedly becomes £45, either the arrangement needs to change or you need to make a deliberate adjustment elsewhere in your budget.
Ask your relative whether the support is working. Are they using the credit as intended? Does the timing match their phone expenses? Would one planned purchase be easier to manage than several small requests? Their answers may help you reduce unnecessary purchases without reducing useful support.
Keep the agreement easy to explain: an affordable maximum, an expected schedule and a rule for exceptions. Revisit it when your income, bills or the recipient’s circumstances change. Supporting family does not require promising an open-ended amount; a dependable contribution that fits your finances is often more sustainable than repeated spending you later struggle to cover.